這課堂由Delft University of Technology的Dr. Pasquale Cirillo 講授。說話速度像是刻意放慢了,講解不會沉悶之餘,初時還有用RSA動畫的方式去解釋事情之間關係。內容方面,沒有涉及複雜的數學證明,某些公式出現時就重申:推導過程不在課程以內,然後直接使用。這令課程變得簡單之餘,也清晰了這是集中在讓初學者理解概念。
The computation of WCDR is performed using the formula you see on your screen. I do agree with you if you think that this formula has somehow fallen from the sky.
That's true: in this course this formula has fallen from the sky. The point is that, in order to derive this formula completely and formally, we would need - all - a big probabilistic apparatus that we do not have, such as for example the copula model. So, that's it: just take this formula for granted.
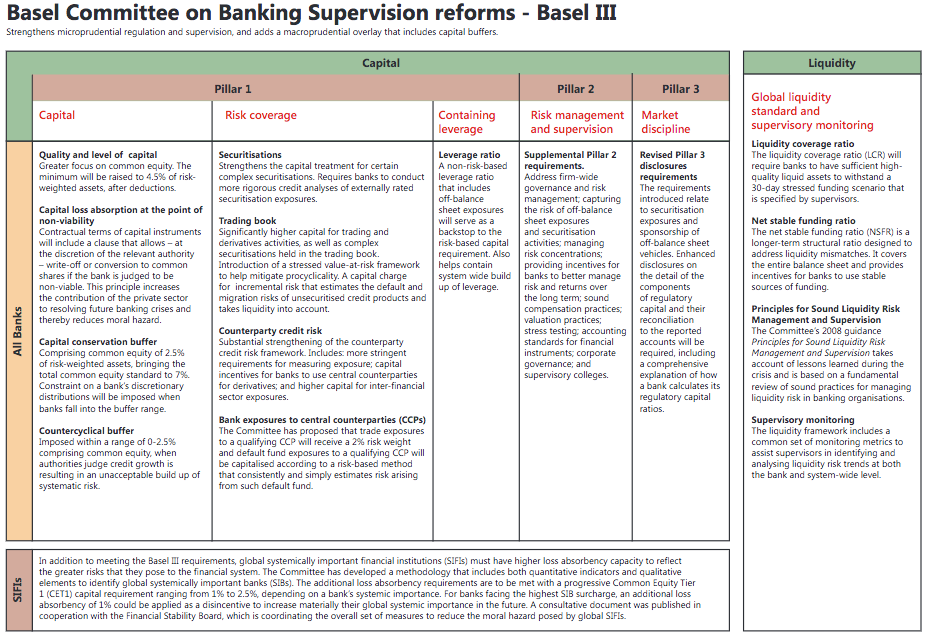
課程把信用風險放在從巴塞爾協定中開始講起。巴塞爾協定是對銀行業的其中一項重要條約。從巴塞爾協定二起,基本定立出三條支柱。
1) Minimum Capital Requirement (Credit Risk, Market Risk, Operational Risk)
2) Supervisory Review Process
3) Market Discipline
更仔細的在:http://www.bis.org/bcbs/basel3/b3summarytable.pdf